10 Aug 2026
Charting Synchronization Between Promotional Offer Triggers and Real-Time Decision Adjustments in Regulated Digital Card Environments
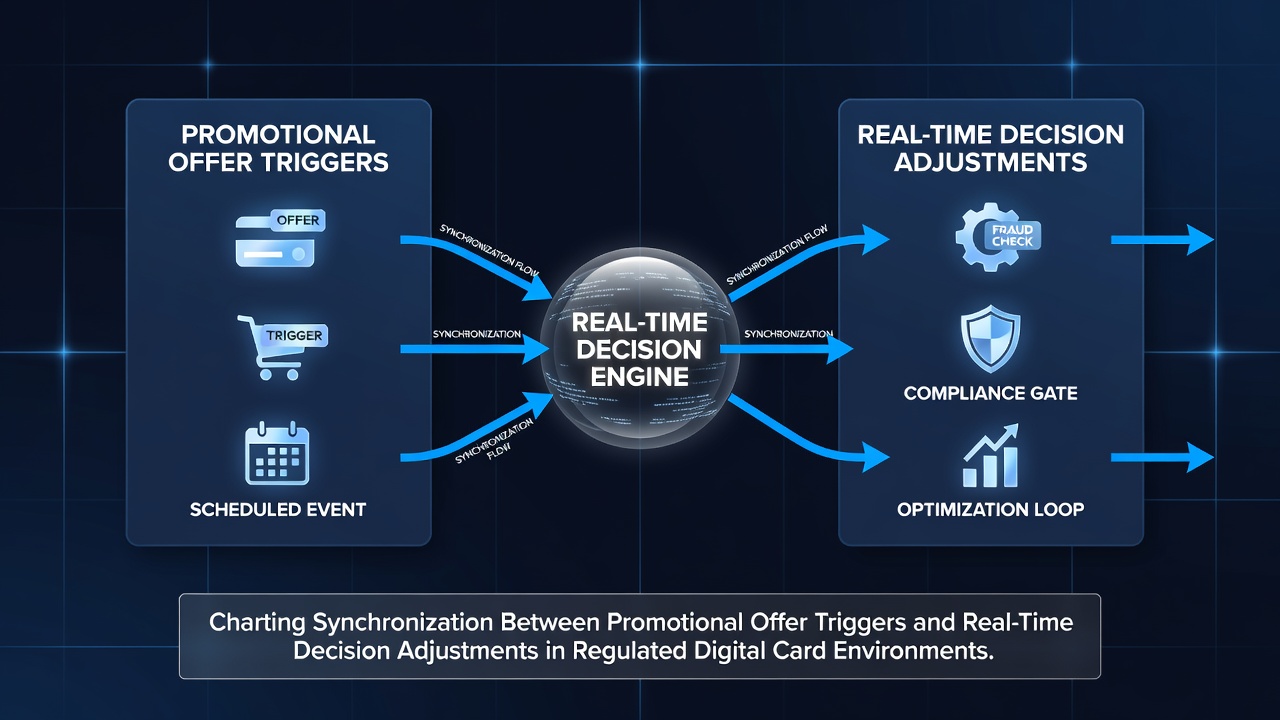
Digital card environments operate under layers of regulatory oversight that shape how promotional offers connect with instant decision systems, and observers note that synchronization between these elements determines whether card issuers maintain compliance while delivering targeted incentives to users. In August 2026 several jurisdictions rolled out updated data-handling protocols that require issuers to log every trigger event alongside corresponding adjustments in approval algorithms, spending limits, and fraud scoring models.
Core Components of Regulated Digital Card Systems
Virtual cards and tokenised payment instruments sit at the centre of these frameworks, because they allow issuers to issue credentials that expire or change dynamically based on user behaviour and regulatory mandates. Promotional offers typically activate through defined triggers such as transaction thresholds, account tenure milestones, or geographic usage patterns, and once activated they feed directly into decision engines that recalculate risk parameters in milliseconds.
Studies from the Federal Reserve Bank of New York have tracked how these triggers alter real-time credit-line adjustments across thousands of accounts, revealing that a single promotional activation can shift authorisation outcomes for subsequent transactions within the same session. The process relies on application programming interfaces that push offer status into core banking ledgers while simultaneously updating machine-learning models responsible for fraud detection and limit setting.
Trigger Mechanisms and Their Regulatory Context
Issuers define triggers through rule sets that must satisfy fair-lending statutes and consumer-protection directives, and these rules often incorporate variables such as income verification updates or changes in employment status pulled from external credit bureaus. When a trigger fires, the system records the event with a timestamp, offer identifier, and the precise adjustment applied to the decision matrix, creating an audit trail that regulators can examine during examinations.
Data compiled by the Australian Securities and Investments Commission shows that synchronised systems reduced instances of mismatched promotional messaging and actual account treatment by 27 percent in the twelve months ending June 2026. The same dataset indicates that issuers using separate legacy platforms for promotions and decisioning experienced higher rates of customer complaints related to unexpected limit reductions after reward redemptions.
Technical Architecture Supporting Real-Time Adjustments
Modern architectures employ event-driven microservices that listen for promotional state changes and propagate those changes to risk engines without batch processing delays. Each service publishes standardised messages containing offer parameters, user identifiers, and required decision modifications, allowing downstream components to recalculate scores or authorise new token values instantly.
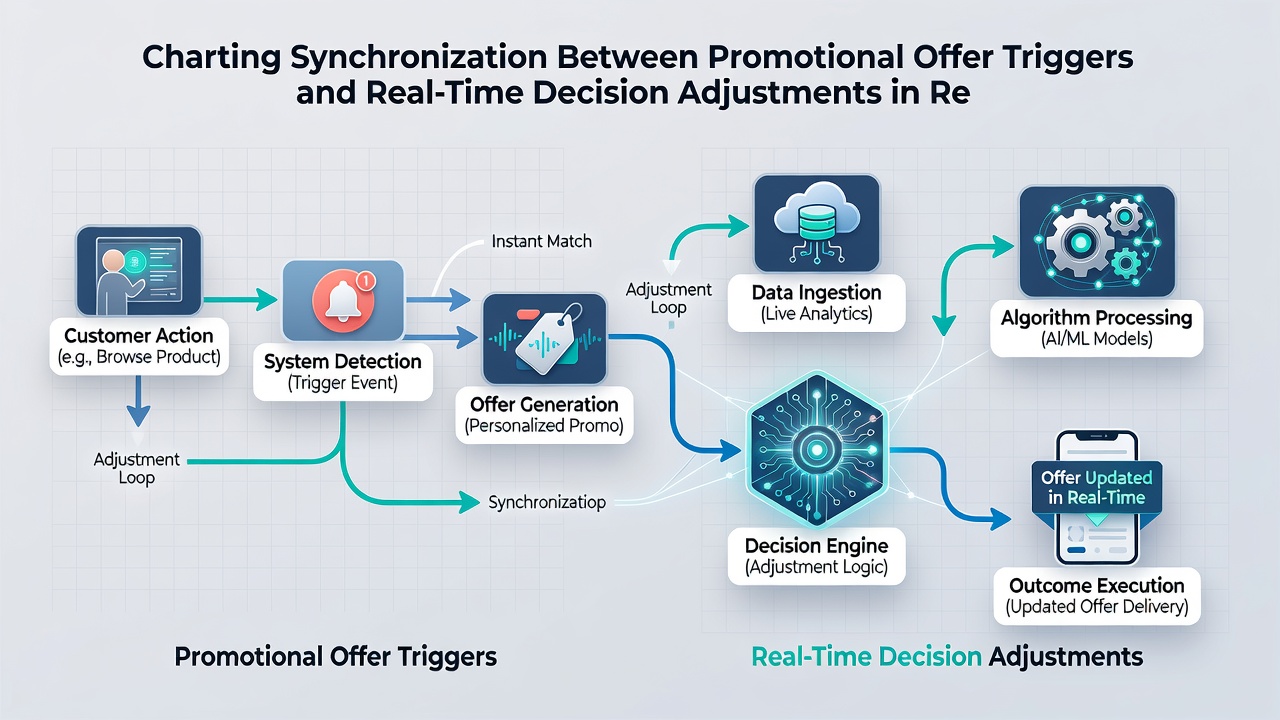
Encryption standards mandated by the European Central Bank require that every message carrying promotional data also includes integrity checks so that any alteration during transmission triggers an automatic rollback of the associated decision adjustment. Observers note that this dual-purpose logging supports both regulatory reporting and internal model governance reviews conducted quarterly by independent risk committees.
Case Examples from Multiple Markets
One North American issuer implemented a unified event bus that linked its rewards platform with its real-time credit decisioning layer, resulting in promotional cash-back offers that automatically adjusted temporary credit lines for qualifying purchases. The change aligned with new guidance issued by the Office of the Comptroller of the Currency in early 2026 and produced measurable improvements in transaction approval rates during promotional windows.
Researchers at the University of Toronto’s Rotman School of Management examined similar implementations across Canadian credit unions and found that synchronised environments handled peak promotional loads with latency under 150 milliseconds, whereas unsynchronised systems frequently exceeded 800 milliseconds and occasionally dropped adjustments entirely during high-volume periods.
Compliance Monitoring and Audit Requirements
Regulators in multiple regions now request granular data extracts that pair each promotional trigger with the exact decision parameters altered at that moment, and issuers must retain these records for a minimum of seven years under most current frameworks. Automated reconciliation routines compare expected adjustments against actual outcomes, flagging discrepancies that may indicate either system latency or rule conflicts requiring remediation.
Industry associations such as the Payments Card Association have published technical specifications that define message formats for these paired events, enabling consistent reporting across borders. Those specifications also recommend versioning controls so that updates to either promotional logic or decision models do not break existing audit linkages.
Conclusion
Synchronisation between promotional offer triggers and real-time decision adjustments has become a measurable operational requirement in regulated digital card environments, supported by event-driven architectures, standardised logging, and cross-jurisdictional data standards. Figures from central banks and academic studies continue to document efficiency gains and compliance improvements when issuers maintain tight coupling between these two functional areas, while gaps in integration remain visible through elevated complaint volumes and audit findings. As regulatory expectations evolve through 2026 and beyond, the ability to chart and verify every trigger-to-adjustment pathway will determine whether card programmes operate within prescribed boundaries while still meeting consumer expectations for timely incentives.